If you want to calculate loan monthly payment, you can use a loan repayment calculator to quickly estimate how much you may need to pay each month. Knowing your estimated monthly payment can help you understand the cost of borrowing and choose a repayment term that fits your budget.
Whether you’re considering a personal loan, car loan, home loan, or another type of installment loan, calculating the monthly payment before borrowing can help you plan ahead.
Calculate Your Loan Monthly Payment
The easiest way to calculate your expected monthly payment is to use an online loan calculator. Our Loan Repayment Calculator lets you enter your loan amount, interest rate, and repayment term to estimate your monthly payment.
Calculate your loan monthly payment with our Loan Repayment Calculator.
Simply enter the required loan information, and the calculator will estimate your monthly repayment.
What Information Do You Need to Calculate a Loan Monthly Payment?
To calculate your loan monthly payment, you generally need three important pieces of information:
1. Loan Amount
The loan amount is the amount you plan to borrow. For example, if you want to borrow $10,000, your loan principal is $10,000.
A larger loan amount generally results in a higher monthly payment when the interest rate and repayment period remain the same.
2. Interest Rate
The interest rate represents the cost of borrowing money and is usually expressed as an annual percentage rate.
For example, a loan with a 6% annual interest rate will generally cost less in interest than a similar loan with a 10% annual interest rate, assuming the other terms are the same.
3. Loan Term
The loan term is the length of time you have to repay the loan. Common terms include 12, 24, 36, 48, 60, and 72 months.
A longer repayment term can reduce the required monthly payment, but it may result in paying more interest over the life of the loan.
How to Calculate Loan Monthly Payment
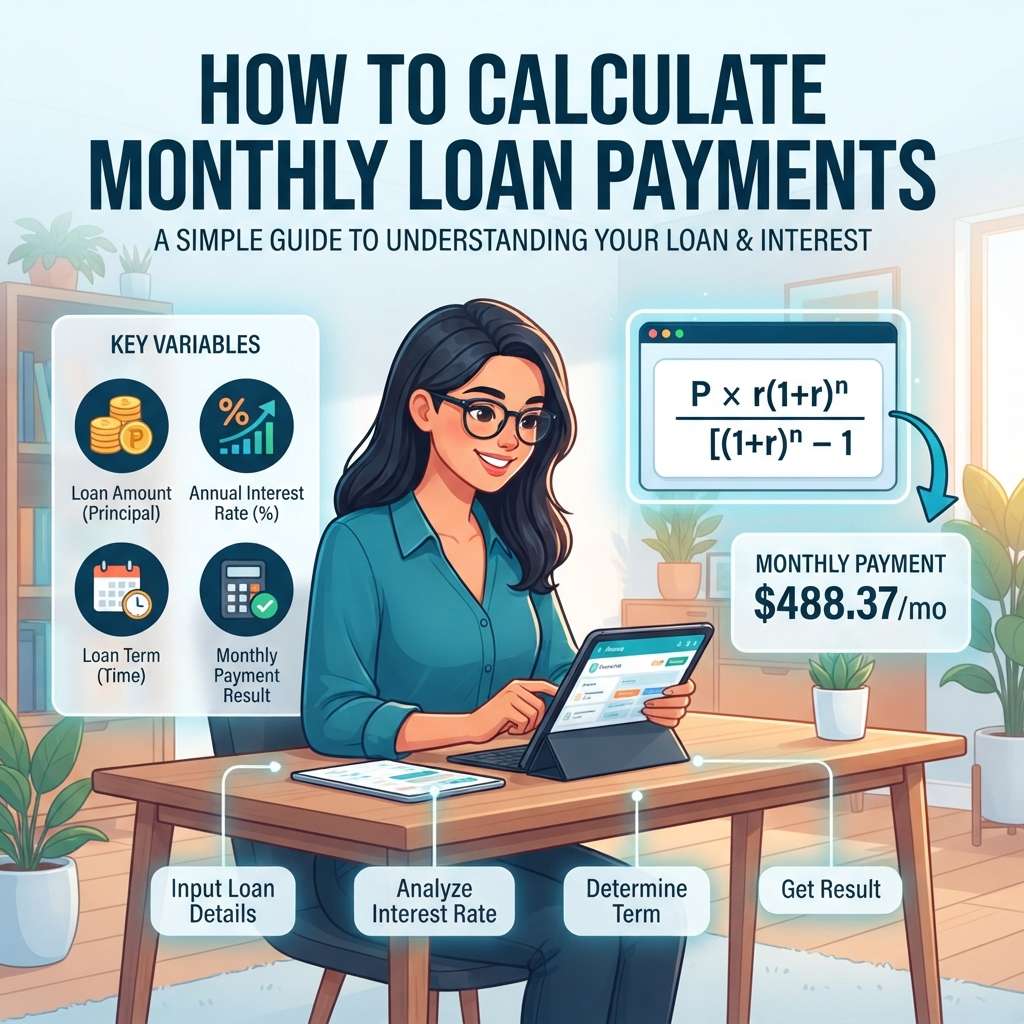
For a standard fixed-rate installment loan, the monthly payment can be calculated using a mathematical formula.
The formula is:
M = P × [r(1 + r)ⁿ] / [(1 + r)ⁿ − 1]
Where:
- M = monthly loan payment
- P = principal loan amount
- r = monthly interest rate
- n = total number of monthly payments
Because the calculation involves several steps, using an online calculator is usually much faster and less prone to calculation errors.
You can use our loan repayment calculator to calculate your estimated monthly payment automatically.
Example of a Monthly Loan Payment Calculation
Suppose you borrow $10,000 at an annual interest rate of 8% for 5 years.
Your loan details would be:
- Loan amount: $10,000
- Annual interest rate: 8%
- Loan term: 5 years
- Number of payments: 60 months
Using the standard loan payment formula, the estimated monthly payment would be approximately $202.76.
The actual amount you pay may differ depending on the lender’s terms, fees, payment schedule, and other loan conditions.
Why Calculate Your Monthly Loan Payment?
Calculating your monthly payment before taking out a loan can help you understand whether the repayment amount fits within your budget.
It can also help you compare different loan amounts and repayment terms.
For example, you can calculate payments for a 3-year loan and a 5-year loan to see how changing the repayment period affects your monthly payment and total interest.
Monthly Payment vs. Total Loan Cost
Your monthly payment is only one part of the cost of a loan.
A loan with a lower monthly payment may have a longer repayment period. Because you make payments for a longer period, you could pay more interest overall.
For example, extending a loan from 36 months to 60 months may reduce the required monthly payment, but the total interest paid could increase.
That’s why it’s useful to look at both:
- Monthly payment
- Total interest
- Total amount repaid
- Loan term
Our Loan Repayment Calculator can help you estimate your repayment based on the information you enter.
How Interest Rates Affect Monthly Payments
The interest rate can have a significant effect on your monthly loan payment.
If two loans have the same principal and repayment term but different interest rates, the loan with the higher interest rate will generally have the higher monthly payment.
For example, a $20,000 loan over the same repayment period will generally have a different monthly payment at 6% than it would at 10%.
This is why it’s important to check the interest rate when comparing loan options.
How Loan Terms Affect Monthly Payments
The repayment term also affects your monthly payment.
A shorter loan term usually means higher monthly payments but fewer payments overall. A longer loan term generally means lower monthly payments but more time for interest to accumulate.
Before choosing a repayment period, consider both the monthly payment and the total cost of the loan.
Can I Calculate a Loan Payment Without a Calculator?
Yes. You can calculate a loan payment manually using the standard loan payment formula. However, doing the calculation by hand can be time-consuming, particularly when comparing multiple loan amounts, interest rates, and repayment terms.
An online calculator makes it easier to test different scenarios.
For a quick estimate, calculate your monthly loan payment here.
Frequently Asked Questions
How do I calculate my loan monthly payment?
Enter your loan amount, interest rate, and repayment term into a loan repayment calculator. The calculator can then estimate your monthly payment based on those values.
What is the formula for calculating a loan monthly payment?
For a standard fixed-rate installment loan, the formula is M = P × [r(1 + r)ⁿ] / [(1 + r)ⁿ − 1], where M is the monthly payment, P is the principal, r is the monthly interest rate, and n is the number of monthly payments.
Does a longer loan term lower the monthly payment?
Generally, yes. A longer repayment term spreads the loan balance across more payments, which can reduce the monthly payment. However, you may pay more interest over the full loan term.
Does a higher interest rate increase the monthly payment?
Generally, yes. If the loan amount and repayment period remain the same, a higher interest rate usually results in a higher monthly payment.
Can I calculate payments for different loan amounts?
Yes. You can enter different loan amounts into a calculator to compare estimated monthly payments.
Is the calculated monthly payment the exact amount I will pay?
Not necessarily. An online calculation is an estimate based on the information entered. Your actual payment may vary because of lender-specific terms, fees, taxes, insurance, payment frequency, or other costs.
Calculate Your Loan Payment Today
Knowing your estimated monthly payment can make it easier to plan for a new loan and compare different repayment options.
Instead of calculating everything manually, use our Loan Repayment Calculator to estimate your monthly payment based on your loan amount, interest rate, and repayment term.